Close Menu
  • Home
  • Financial
  • News
  • Personal Finance
  • Real Estate
  • Debt Relief
  • Subscribe Now
What's Hot

How Scott Bessent used financial engineering to fund the $2 trillion deficit while leaving it untouched | Fortune

August 8, 2026

Tips for Negotiating the Best Deal on a New Construction Home

August 7, 2026

In AI-obsessed Silicon Valley, live commerce platform Whatnot just notched a new funding round valuing it at $20 billion | Fortune

August 7, 2026
Facebook X (Twitter) Instagram
creditreddit.org
Subscribe Now
  • Home
  • Financial
  • News
  • Personal Finance
  • Real Estate
  • Debt Relief
  • Subscribe Now
creditreddit.org
Home » Fannie Mae & Freddie Mac Boldly Remove Minimum FICO Requirements—Here’s Why That’s a Big Deal
Personal Finance

Fannie Mae & Freddie Mac Boldly Remove Minimum FICO Requirements—Here’s Why That’s a Big Deal

joshBy joshNovember 24, 2025No Comments3 Mins Read0 Views
Facebook Twitter Pinterest Telegram LinkedIn Tumblr Copy Link Email
Follow Us
Google News Flipboard
Fannie Mae & Freddie Mac Boldly Remove Minimum FICO Requirements—Here’s Why That’s a Big Deal
Share
Facebook Twitter LinkedIn Pinterest Email Copy Link


In This Article

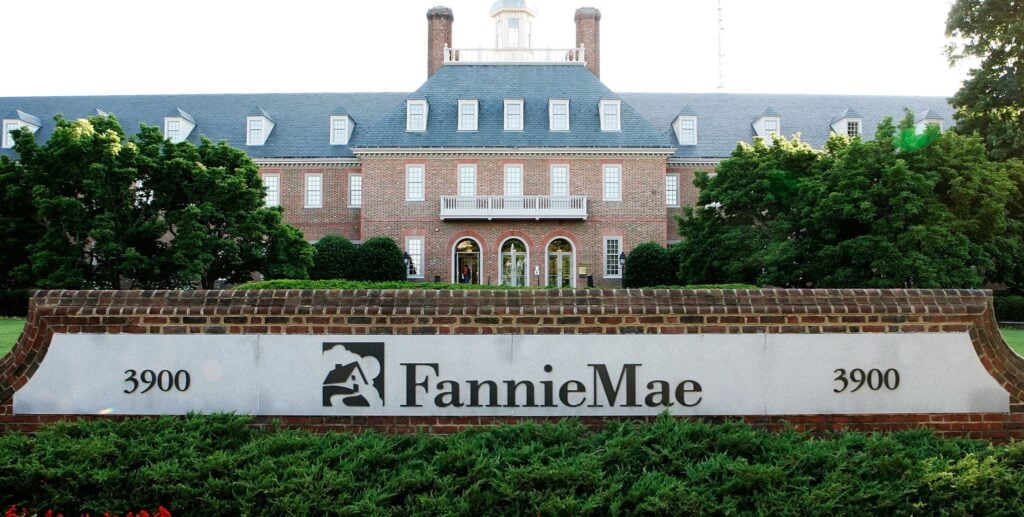
Remarkably, Fannie Mae has officially removed the 620 minimum FICO requirement for Desktop Underwriter (DU) submissions, aligning their approach with Freddie Mac’s LPA as of Nov. 15. Approvals are now determined entirely by DU/LPA findings rather than a hard credit score cutoff. Strong compensating factors have the largest impact toward obtaining A/E findings—e.g., larger down payments, shorter terms, excess assets, etc.

Within the first week, some top national lenders reported the following: 

Many approved applications came in with sub-620 FICOs—roughly 6% of overall application volume—with some as low as 490.

Several brokerages have already begun reevaluating their “fallout” files from the last 60 to 180 days, finding early wins among clients previously declined due to credit.

The 620 minimum credit score requirement—both for single borrowers and the average median score for multiple borrowers—was eliminated for new loan casefiles created on or after Nov. 16, 2025. 

Why Does This Matter to Investors?

The Trump administration is making a concentrated effort to loosen credit and make borrowing more accessible and affordable. 

Another example of expanding affordability is 50-year mortgages and, perhaps more important, mortgage portability. There are active discussions on how to enable homeowners to take their mortgages with them, similar to how consumers can port their cell phone numbers from carrier to carrier. The plan moves with them instead of the mortgage staying with the property. 

This is a novel idea that could have a major impact on inventory. It is estimated that one-third of U.S. borrowers have a mortgage under 4%, creating a “lock-in” effect, with downstream inventory constraints. 

By enabling borrowers to port their pandemic-era low-rate mortgages to either a downsized or upsized property, transactional activity would likely increase while relieving price pressures in some regions. 

Conversely, there are many considerations for how these programs would be implemented, and whether they would actually level the market or skew favorability toward those with lower mortgage rates. 

In the upsizing scenario, guidelines would need to be set for the property type. Could a primary mortgage be ported to an investment property, maybe after a certain period? And if the current loan balance was insufficient to cover the down payment difference on the purchase, will a second-lien program be introduced at more favorable rates? Otherwise, if the spread is large enough, the blended rate could actually be higher than a fresh conventional loan, albeit with the potential for extended amortization. 

From a lender and servicing perspective, mortgage notes would be much more likely to be held to maturity, which could influence rates or loan costs, and new guidelines would be instituted for a new class of borrowers. 

What to Do Now

Real estate investors should pay particular attention to developments in mortgage markets heading into and through 2026, as any significant revisions to “business as usual” could provide tight windows of opportunity to execute. Think of when rates bottomed during the pandemic, or the recently reimplemented 100% bonus depreciation for qualified and participating short-term rental acquisitions. 

Anyone on the qualifying FICO fence, or who was recently declined for conventional loan programs as a result of credit score, including FHA programs, should check in with their lender for an updated prequalification or approval letter.

You might also like

big Boldly Deal Fannie FICO Freddie Mac Mae Minimum Remove RequirementsHeres
Follow on Google News Follow on Flipboard
Share. Facebook Twitter Pinterest LinkedIn Telegram Email Copy Link
josh
  • Website

Related Posts

Tips for Negotiating the Best Deal on a New Construction Home

By joshAugust 7, 2026

The 7-Property Retirement Plan ($80,000/Year)

By joshAugust 7, 2026

Vacation Rentals Are Officially on Sale: Where They’re Worth Buying

By joshAugust 6, 2026

How to Build Your Own Real Estate Investing Team (From Scratch)

By joshAugust 5, 2026

2026’s “Discounted” Properties Aren’t the Bargain They Look Like

By joshAugust 4, 2026

“Sweet Spot” Rentals Every Rookie Should Buy

By joshAugust 4, 2026
Add A Comment
Leave A Reply Cancel Reply

Top Posts

How to Build a More Predictable Financial Routine

November 24, 2025234 Views

Social Security payments to go up 2.8% next year while polls show three-fourths of seniors think 3% isn’t enough to keep up with rising prices | Fortune

October 24, 202542 Views

Trump Floats 50-Year Mortgages: Cash Flow Boost or Affordability Illusion?

November 13, 202540 Views

Why Mortgage Rates are Rising as the Fed Keeps Cutting

November 4, 202533 Views
Don't Miss

How Scott Bessent used financial engineering to fund the $2 trillion deficit while leaving it untouched | Fortune

August 8, 20264 Mins Read0 Views

While investors fixate on the AI boom, a warning from a group of Wall Street…

Tips for Negotiating the Best Deal on a New Construction Home

August 7, 2026

In AI-obsessed Silicon Valley, live commerce platform Whatnot just notched a new funding round valuing it at $20 billion | Fortune

August 7, 2026

The 7-Property Retirement Plan ($80,000/Year)

August 7, 2026
Demo
Our Picks

How Scott Bessent used financial engineering to fund the $2 trillion deficit while leaving it untouched | Fortune

August 8, 2026

Tips for Negotiating the Best Deal on a New Construction Home

August 7, 2026

In AI-obsessed Silicon Valley, live commerce platform Whatnot just notched a new funding round valuing it at $20 billion | Fortune

August 7, 2026
Most Popular

Investors Are Controlling the Housing Market

September 4, 20250 Views

Local Politics is Ruining the American Dream With Overbearing Regulations

September 4, 20250 Views

A New Law Forces Landlords to Change Practices in Massachusetts. While Other States Join, Here’s How to Stay Compliant

September 4, 20250 Views
  • Home
  • Privacy Policy
  • Terms and Conditions
  • Subscribe Now
© 2026 ThemeSphere.

Terms & Conditions | Privacy Policy

Type above and press Enter to search. Press Esc to cancel.